The definitive resource for municipal bond investors.
Research-driven education on tax-exempt investing, credit analysis and fixed income portfolio strategy — written by professionals, read by 180,000 investors and advisors each month.
The quiet engine of American public infrastructure.
Every school built, water main replaced, and hospital financed in the United States has, somewhere along the way, been paid for with municipal bonds. For investors, that same market delivers something scarce: predictable, tax-advantaged income backed by essential public services.
We publish independent, professional-grade education so individuals and their advisors can navigate the muni market with the same clarity institutional buyers use every day.
Read the definitive guideFederal (and often state) tax-exempt interest — the highest-value structure in fixed income for taxable investors.
Investment-grade munis default at roughly a tenth the rate of corporates with the same rating letter.
Water, sewer, electric and general obligation credits backed by taxing power or monopolistic revenue.
Scheduled coupons, defined maturities, and a laddered structure that removes market timing from the equation.
Where the muni market sits today.
A quick view of the state of the market — benchmark yields, spreads and issuance — updated in every weekly Muni Brief.
The 2026 muni story so far
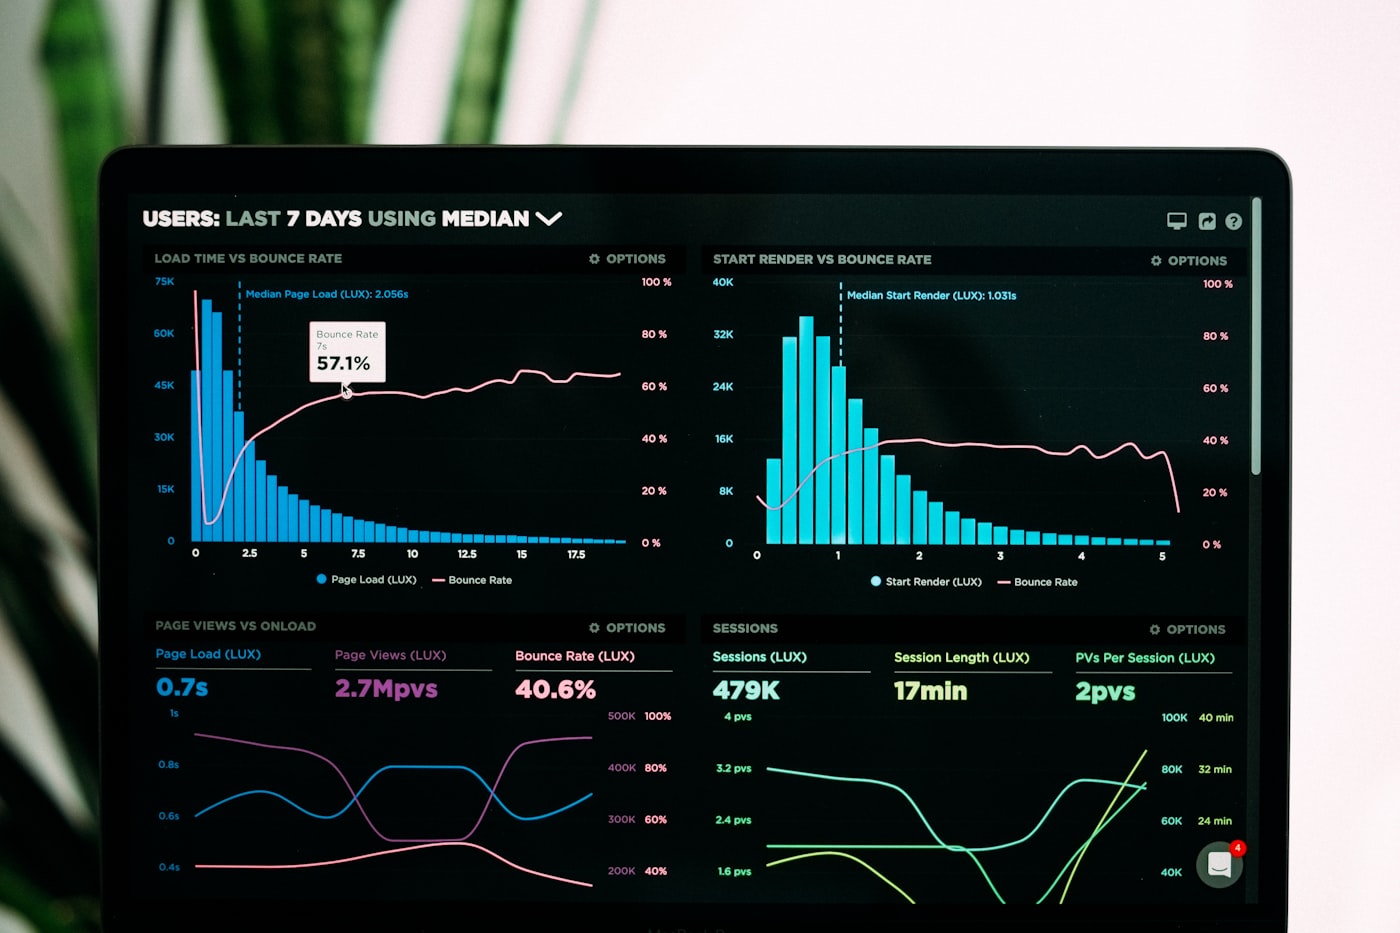
Yields have compressed roughly 40 basis points from year-end 2025 levels as Fed cuts filter through the front end of the curve. Credit spreads sit at 5-year tights, and the primary calendar has run 12% ahead of the same period last year.
Read the latest market coverageFive families of municipal bonds every investor should know.
The muni market is not monolithic. Each family has a distinct security structure, risk profile, and role in a diversified fixed income portfolio.
Backed by the full faith, credit and taxing power of the issuing government. The market's benchmark security.
Backed by cash flows from a specific project — water, sewer, transit, toll road, airport.
The standard structure: federally exempt, often state exempt for in-state buyers.
Federally taxable; useful for advance refunding and pension obligation bonds.
Mutual funds, ETFs and defined-maturity funds for diversified exposure without CUSIP selection.
From bridge to portfolio: the muni lifecycle.
- 1The issuer identifies a project
A city, county, school district or authority determines it needs to finance a capital project — a new school, a water treatment upgrade, a subway extension.
- 2The bond is structured and underwritten
Financial advisors, bond counsel and an underwriting syndicate structure the security: maturity schedule, coupon, call provisions, and security pledge.
- 3The bond sells into the market
During the retail order period, individual investors submit orders; institutional allocations follow. New-issue bonds price at par with a stated coupon.
- 4Coupons are paid on schedule
Semi-annual interest is paid over the life of the bond, funded by tax revenue (GO) or project cash flows (revenue).
- 5Principal returns at maturity
The investor's principal is returned at par at final maturity, or earlier if the bond is called during a redemption window.
Understand what you're being paid to take on.
Bond prices fall when rates rise. Duration measures the sensitivity.
Ladder maturities; match duration to time horizon.
The issuer's ability to pay may weaken over time.
Diversify across 20+ issuers; monitor EMMA notices.
Most munis can be redeemed early; you may lose above-market coupons.
Evaluate on yield to worst; buy non-callable when available.
Odd-lot bonds can be expensive to sell in stressed markets.
Use competitive bid platforms; keep a fund sleeve for liquidity.
Where to start, whatever your experience level.
New to municipal bonds?
Start with our pillar guide — market structure, security types and the tax exemption explained without jargon.
Advisors and RIAs
Our strategy library covers laddering, tax-loss harvesting, credit surveillance and portfolio construction frameworks.
Active investors
Weekly market coverage, credit deep-dives, and long-form ideas — everything we publish in one place.
A muni allocation isn't one-size-fits-all.
How much of your fixed income sleeve belongs in municipal bonds depends on your marginal tax bracket, your state of residence, and your account structure. The higher your bracket and the more of your assets sit in taxable accounts, the larger the muni allocation typically makes sense.
Illustrative allocations of the fixed income sleeve for taxable brokerage accounts. Not personalized advice.
The public projects that anchor the market.
Fresh from the editorial desk.
What Is a Bid Bond and How Does It Work?
A bid bond is a short-term guarantee that a contractor who wins a public project will actually sign the contract and provide the required performance and payment bonds. It is issued by a surety company on the contractor's behalf, and it protects the project owner financially if the winning bidder backs out after the award.
How to Buy Municipal Bonds: A Practical Investor's Guide
Buying a municipal bond is more than clicking a ticker. From CUSIP-level due diligence to reading the official statement, here is the practical process professional fixed income buyers use.
Selling Municipal Bonds: When to Trade Out and How to Do It Well
Most retail muni investors buy and hold. When you do need to sell — for tax loss harvesting, credit deterioration or a life event — the mechanics matter enormously.
Active Municipal Bond Management: A Framework for Adding Value
The muni market is fragmented, opaque and highly retail-driven — the exact conditions where active management can still add alpha. Here is the framework professionals use.
"The clearest, most rigorous plain-English education on the muni market I've found. I send new advisors here in their first week."
Common questions about municipal bonds.
Longer answers to these — and dozens more — live in our pillar guides and the article archive.
Read the full guide